
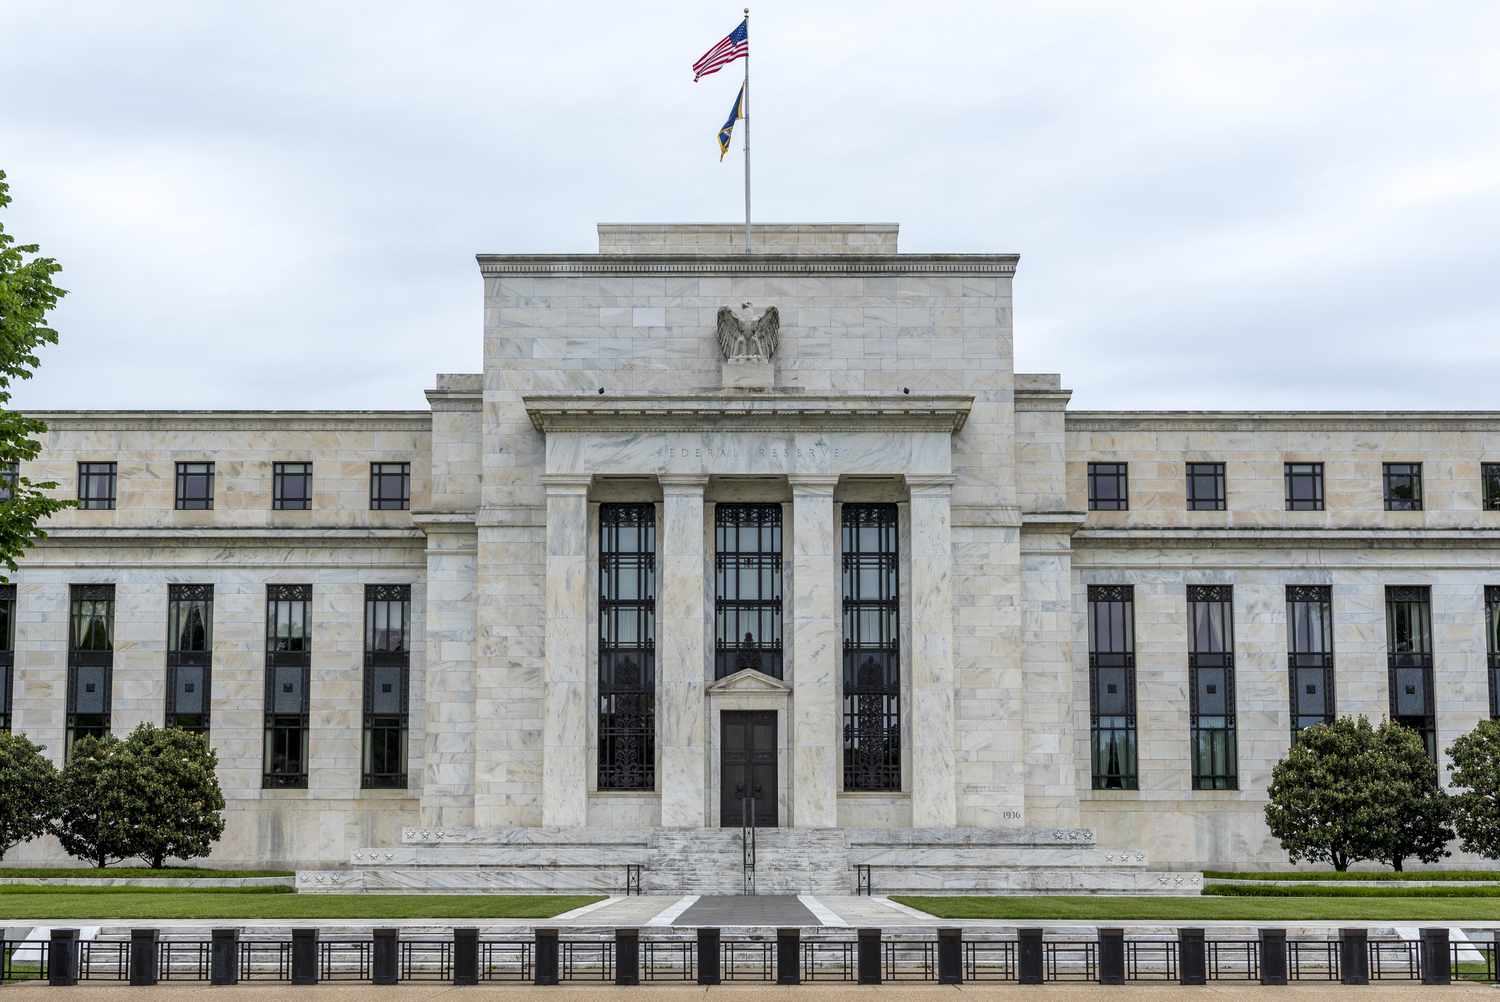
The Federal Reserve enters September facing a difficult balancing act. Financial markets are closely watching the U.S. August jobs report due today, with investors seeking clues on whether the labour market is weakening enough to justify a more accommodative monetary policy stance. At the same time, inflation remains above the Federal Reserve’s 2% target, while renewed geopolitical tensions have pushed oil prices higher, threatening to reignite price pressures. The combination leaves policymakers navigating a narrow path between supporting economic growth and preventing inflation from becoming entrenched.
The labour market has already shown signs of cooling. U.S. nonfarm payroll employment declined by 23,000 in July, while the unemployment rate remained at 4.1%, according to the Bureau of Labor Statistics. Economists expect August employment to have rebounded modestly, with forecasts pointing to roughly 50,000–60,000 new jobs and an unemployment rate of 4.1%. A weaker-than-expected report could strengthen the case for keeping rates unchanged or eventually easing policy, while a stronger reading could reinforce concerns that the economy remains sufficiently resilient to withstand higher rates.
Inflation, however, complicates the picture. Federal Reserve Governor Christopher Waller has indicated that he could support keeping rates unchanged at the September meeting if incoming inflation data show continued improvement, although a renewed acceleration in prices could alter that position. The Fed’s preferred inflation measure remains elevated, while policymakers are also contending with the risk that higher energy prices could slow the disinflation process. Oil prices have risen amid renewed Middle East tensions, adding another potential source of pressure through transportation, production and household costs. The Fed itself has previously highlighted the impact of the oil shock on its policy outlook.
This creates a three-way policy dilemma: employment, inflation and interest rates. If employment deteriorates significantly while inflation continues to moderate, the Fed could have greater room to ease policy. Conversely, resilient employment combined with persistent inflation and higher oil prices could keep policymakers cautious and potentially prolong restrictive monetary conditions. For investors, the implications extend across equities, bonds, currencies and commodities because expectations around the Fed directly influence global financial conditions.
For emerging markets such as Kenya, the outcome matters through several channels. A more dovish Fed could weaken the U.S. dollar, encourage capital flows toward emerging markets and reduce pressure on countries reliant on external financing. Lower U.S. Treasury yields could also improve the relative attractiveness of emerging-market bonds and equities. Conversely, a hawkish Fed could strengthen the dollar, increase global yields and encourage investors to favour U.S. assets, potentially creating pressure on emerging-market currencies and capital flows.
Kenya enters this environment with its Central Bank Rate at 8.75% and inflation at 6.6% in August. This means global monetary conditions remain an important consideration even as domestic policy is driven primarily by local inflation and growth dynamics. For Kenyan investors, therefore, the Fed’s September decision is not simply a U.S. story. It is a reminder that portfolio positioning increasingly requires watching the interaction between global rates, commodity prices, currencies and domestic fundamentals.