
Revenue Growth and Value Capture in Digital Financial Services
In the digital financial services sector, revenue growth is often treated as a direct signal of business success. However, in many fintech models, especially within payments ecosystems, revenue growth does not always reflect true economic performance. A proper assessment requires separating headline growth from the underlying economics of value creation and value capture.
Transaction-Driven Growth in Fintech Ecosystems
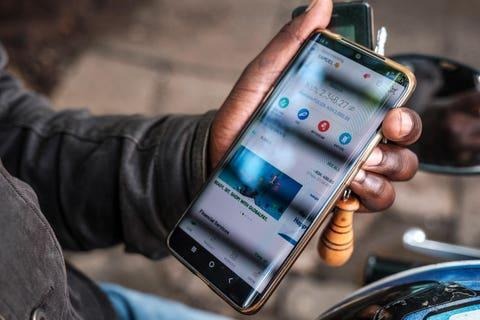
Fintech growth is largely driven by transaction volumes rather than high-margin revenue streams. In Kenya’s mobile money ecosystem, Safaricom’s M-Pesa processes an estimated Kshs. 8.3 trillion in transaction value over a recent reporting period. Despite this scale, the revenue generated remains relatively small in proportion to total flows. M-Pesa contributes approximately Kshs. 150–160 billion annually in service revenue within Safaricom’s overall earnings structure. This contrast highlights the gap between transaction scale and monetization capacity in digital payments systems.
Structural Limits of Monetization in Digital Payments
Digital payment platforms facilitate large-scale movement of money, but they do not capture a proportional share of the value they enable. This limitation arises from low transaction fees, regulatory constraints, and the commoditized nature of basic payment services. As a result, high transaction activity does not automatically translate into equivalent revenue growth or profitability. The platform acts primarily as infrastructure rather than a direct value extractor from each transaction.
The Role of Incentives and Subsidized Growth
Many fintech firms also rely on customer acquisition incentives and subsidized usage to accelerate adoption. These strategies successfully increase transaction volumes and deepen ecosystem penetration. However, they can also distort short-term performance indicators by inflating usage metrics without reflecting sustainable profitability. This makes it important to distinguish between organic demand-driven growth and growth supported by promotional or structural subsidies.
Investment Implications and Unit Economics
From an investment perspective, these dynamics highlight the importance of evaluating fintech companies beyond headline revenue figures. A more accurate assessment focuses on unit economics, including customer acquisition cost (CAC), lifetime value (LTV), transaction margins, and the ability to generate operating leverage at scale. These indicators provide a clearer view of long-term financial sustainability than revenue growth alone.
From Payment Scale to Value Creation
High transaction volumes, such as those seen in the M-Pesa ecosystem, indicate strong adoption and market dominance. However, they do not automatically translate into proportional revenue or profit growth relative to the value of transactions processed. Sustainable value creation in fintech is more likely to emerge from higher-margin services built on top of payment infrastructure, including lending, merchant services, savings products, and data-driven financial solutions. For investors, separating transaction scale from true value capture remains essential in identifying durable winners in the digital payments landscape.