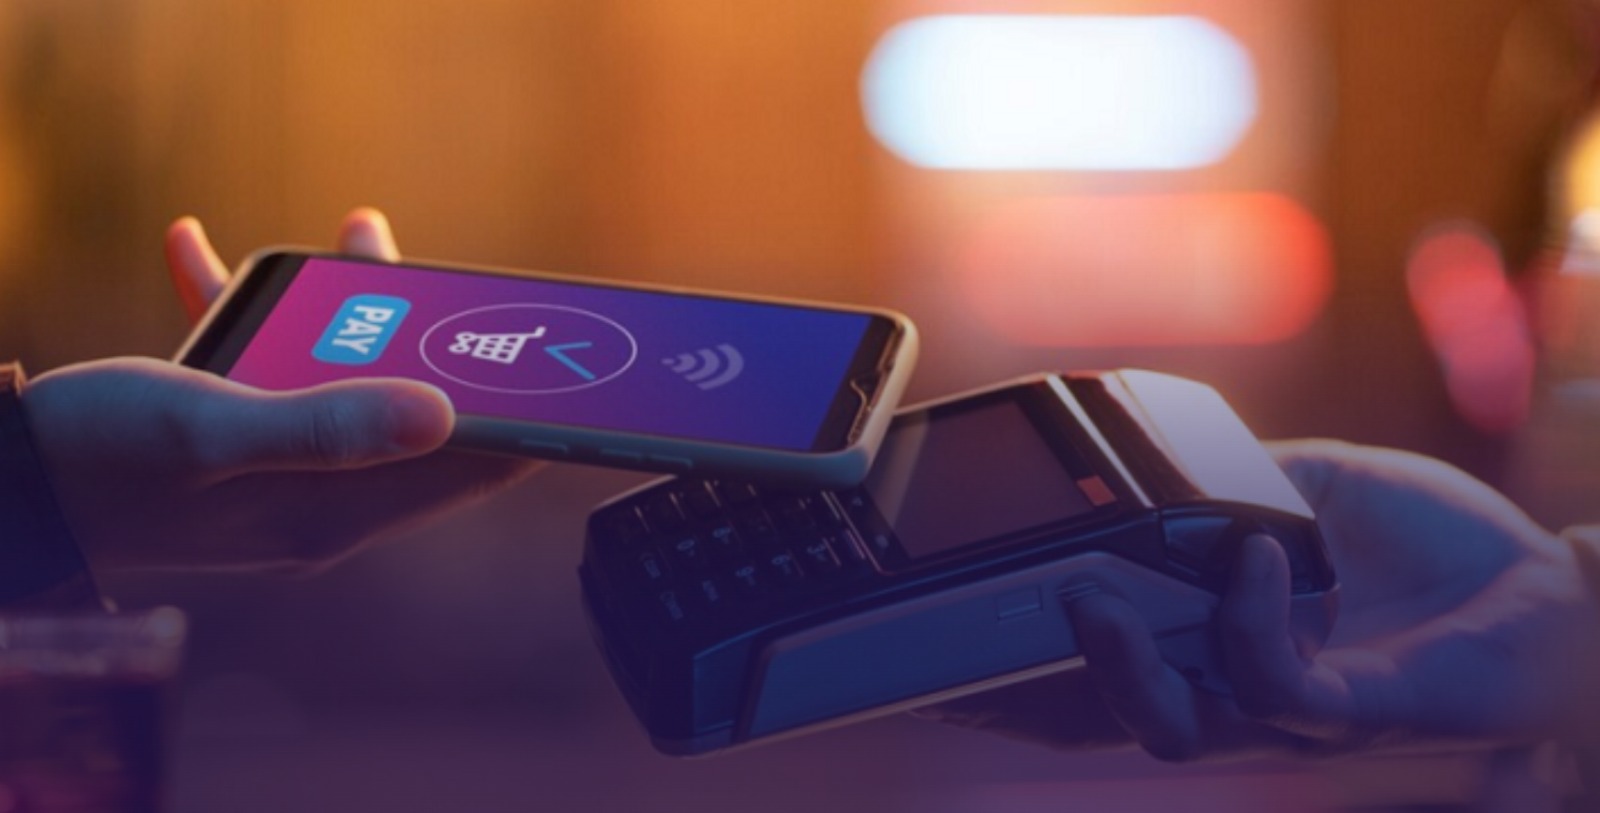
Digital payments are rapidly changing how money moves across the world, and stablecoins are increasingly becoming part of that transformation. What was once largely associated with cryptocurrency trading is now finding practical applications in business payments, treasury management and cross-border commerce.
Recent data highlighted in Cytonn’s Q3’2026 Markets Review shows the growing role of stablecoins in payments. During FY2026, approximately 17.0% of stablecoin-linked card volume year-to-date came from business and commercial card programmes, while payment volumes across more than 160 stablecoin-linked card programmes grew by nearly 200.0% year-on-year.
This growth points to a broader shift in how stablecoins are being used. Rather than serving primarily as digital assets for trading, stablecoins are increasingly being explored as tools for moving and settling money. Their ability to maintain a relatively stable value, often by being linked to currencies such as the US dollar, makes them attractive for transactions where speed and value stability are important.
For businesses operating across borders, this could be particularly significant. Traditional international payments can involve multiple intermediaries, different banking systems and lengthy settlement periods. Stablecoin-based payment infrastructure offers an alternative that can potentially make cross-border transactions faster and more efficient.
Kenya is also well positioned to participate in this evolution. The country has already developed a strong digital payments ecosystem, driven by widespread mobile money adoption, digital banking and alternative payment channels. The continued digitisation of financial services is evident across the banking sector, with a growing share of transactions taking place through digital platforms rather than physical branches.
Cross-border payment infrastructure is also evolving. In February 2026, PesaLink partnered with the Pan-African Payment and Settlement System (PAPSS) to facilitate instant, 24/7 cross-border payments in local currencies. The partnership connects more than 80 PesaLink network participants to over 160 PAPSS participating banks, supporting greater interoperability across African financial systems.
As these technologies develop, regulation will become increasingly important. Kenya’s Virtual Asset Service Providers Regulations, 2026, establish a licensing framework for virtual asset activities, including payment processors, custodial wallets, exchanges, tokenisation platforms and stablecoins. The framework also introduces requirements around capital, customer asset protection and anti-money laundering and counter-terrorism financing controls.
For consumers and businesses, the significance of these developments may ultimately extend beyond the technology itself. Faster payments, more efficient cross-border transactions and greater accessibility could reshape how individuals and businesses interact with financial services.
The growing adoption of stablecoin-linked payment programmes suggests that this transformation is already underway. As digital payment infrastructure continues to develop and regulation becomes clearer, traditional financial systems and digital assets are likely to become increasingly interconnected.
The future of payments may therefore not be about choosing between traditional finance and digital assets, but about how effectively the two can work together to make moving money faster, simpler and more efficient.