
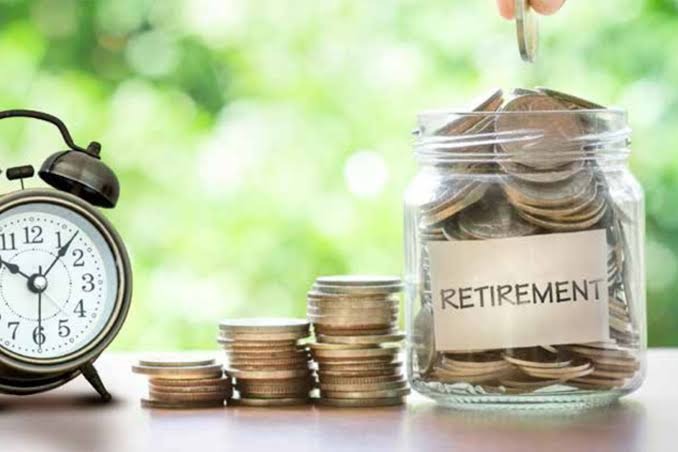
Retirement planning is often associated with making regular pension contributions and watching the accumulated savings grow over time. However, saving for retirement is only one part of the journey. The real objective is to ensure that these accumulated contributions can eventually provide a reliable and sustainable source of income during retirement.
Throughout your working years, pension contributions are invested across different asset classes with the objective of generating returns and growing members’ retirement savings. Consistent contributions, investment returns and the power of compounding can significantly increase the value of retirement savings over time. This highlights the importance of starting early and maintaining regular contributions throughout one’s working life.
Upon retirement, members can access their accumulated benefits in accordance with the rules of their retirement benefits scheme and applicable regulations. Depending on the arrangement, a member may access part of their benefits as a lump sum, while the remaining savings can be used to generate regular retirement income. Making this transition effectively requires careful consideration of how much income will be needed and how long the accumulated savings should last.
One option for generating retirement income is an annuity, which can provide regular payments throughout retirement. This can help retirees meet recurring expenses such as food, housing, healthcare and other living costs. The level of income will depend on factors including the amount accumulated, the selected arrangement and prevailing market conditions.
However, retirement income planning should go beyond simply deciding how much to withdraw. Retirees also need to consider inflation, healthcare costs, longevity and investment performance. With people potentially spending several decades in retirement, withdrawing funds too quickly could increase the risk of exhausting their savings. A well-planned retirement income strategy can therefore help balance current financial needs with the preservation of savings for the future.
This is where having a well-structured retirement benefits scheme becomes important. The Cytonn Umbrella Retirement Benefits Scheme (CURBS) provides employers and employees with a flexible platform for building retirement savings while benefiting from professional fund management, regular member statements and retirement planning support. The scheme also provides members with tools and personalized projections that can help them understand how their current contributions could translate into future retirement income.
Ultimately, pension planning should not only focus on how much you contribute, but also on how those contributions will support you once employment ends. Starting early, contributing consistently and having a clear retirement income strategy can help turn accumulated pension savings into a sustainable source of income. With the right retirement benefits structure and professional guidance, members can approach retirement with greater clarity and confidence.