Digital Identity Infrastructure and Trust in Modern Financial Systems
Digital identity infrastructure and trust sit at the center of every financial interaction. In digital financial systems, transactions occur without physical contact and decisions are executed in real time, meaning that trust is no longer established through face-to-face verification but through structured digital identity systems and automated risk controls. As financial ecosystems have evolved from branch-based models in the early 2000s to fully digitized platforms in the 2020s, identity verification, fraud detection, and real-time compliance have become essential components of system stability, directly shaping how securely digital payments and credit systems can scale.
Early Identity Verification in Financial Systems
In the early 2000s, identity verification in financial services was largely based on physical processes, where banks relied on in-person onboarding, paper documentation, and manual validation against national identity records. While this provided a controlled verification environment, it also introduced structural limitations, particularly in emerging economies where formal addressing systems and comprehensive documentation coverage were incomplete, thereby constraining financial inclusion and slowing the expansion of formal financial services.
Digital Identity Infrastructure and the Rise of Mobile Money
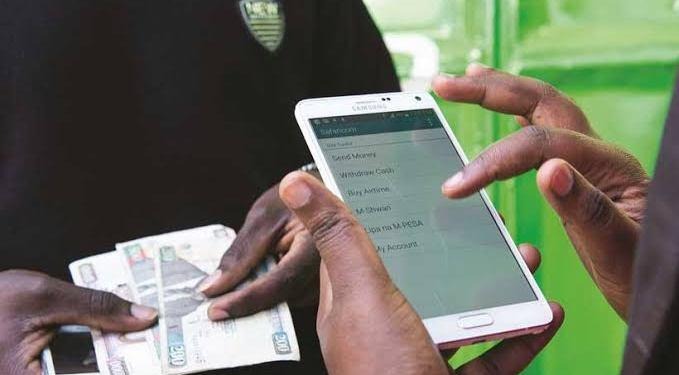
Between the early and mid-2010s, financial systems began shifting toward digital identity verification frameworks. In Kenya, the rapid expansion of mobile money systems such as M-Pesa enabled large-scale onboarding processes linked to SIM registration and national identification databases, significantly reducing account activation time while expanding access to financial services across previously underserved populations. During this period, Know Your Customer (KYC) processes became increasingly digitized, allowing financial institutions and mobile money operators to rely on agent networks and electronic verification systems rather than physical bank branches.
Continuous Verification in Modern Systems
From the late 2010s into the early 2020s, identity systems evolved beyond static onboarding checks toward continuous verification models, where financial platforms increasingly integrated behavioral and transactional data into real-time risk frameworks. Variables such as transaction frequency, spending patterns, device fingerprints, login behavior, and geolocation consistency became core inputs for anomaly detection systems, enabling institutions to detect fraud dynamically while maintaining seamless user experience for legitimate customers. In Kenya’s mobile money and digital lending ecosystems, these systems improved operational efficiency while reducing systemic fraud exposure.
Global Fintech and Regulatory Integration
Globally, fintech infrastructure providers accelerated this transformation by embedding advanced identity verification tools into financial platforms. Between 2016 and 2023, firms such as Stripe, PayPal, and Revolut implemented systems combining biometric authentication, document verification, and machine learning-based risk scoring, enabling real-time identity validation and transaction screening while reducing onboarding delays and improving fraud detection efficiency across digital payment networks.
Regulatory frameworks between 2015 and 2025 further reinforced the integration of identity infrastructure into financial systems. In Kenya, institutions such as the Central Bank of Kenya and the Communications Authority strengthened SIM registration requirements, anti-money laundering controls, and transaction monitoring systems, ensuring that rapid digital financial expansion remained aligned with compliance and systemic risk oversight.
Scalability, Risk, and System Stability
From a systemic perspective, digital identity infrastructure functions as a critical determinant of scalability in fintech ecosystems, as platforms that integrate identity verification, fraud detection, and behavioral analytics into unified systems achieve higher transaction security, faster onboarding, and improved operational efficiency. This integration strengthens system resilience by reducing exposure to fraud and minimizing operational disruptions while supporting higher transaction volumes across digital financial networks.
However, increased reliance on digital identity systems also introduces structural vulnerabilities, including centralized identity databases that concentrate risk, heightened privacy exposure, and potential verification system failures that may propagate across interconnected platforms, amplifying systemic disruption.
Digital identity infrastructure therefore functions as a foundational control layer within modern financial systems, shaping how financial ecosystems scale while maintaining stability and ensuring that transactions, credit decisions, and broader financial interactions remain anchored in verified identity and structured risk governance frameworks.