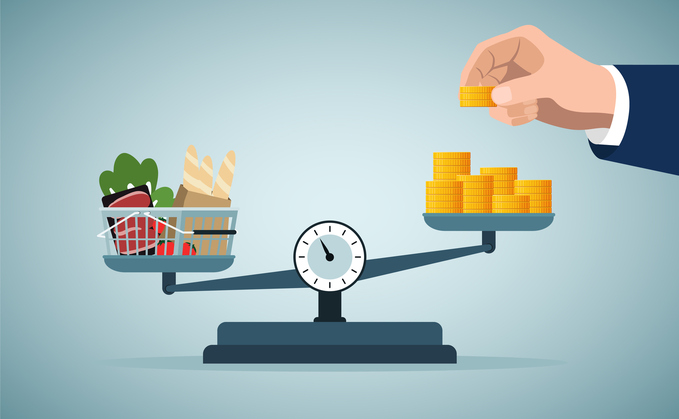
The cost of living crisis is forcing many people to rethink their budgets. For a growing number of workers, pension contributions are among the first things to be cut. This may bring short-term relief, but the long-term consequences can be serious. Retirement saving is not something that can be paused without a cost, even if that cost remains invisible for years.
When everyday costs rise, there is simply less money left at the end of the month. Food, energy, rent, and transport are taking up more of people’s incomes than ever before. In this environment, saving for retirement can start to feel less urgent. Many people reduce or pause their pension contributions just to get by. It feels like a practical decision in the moment, but the financial cost later in life can be far greater than expected. What starts as a temporary measure can quietly become a long-term habit if financial pressures persist.
This is especially true for younger workers. Money saved early has more time to grow. Even a short break from contributing during the early years of a career can leave a noticeable gap in a pension pot by retirement. The effect of lost contributions builds up quietly over time and is easy to underestimate. Compounding works in your favor when you stay consistent, but it works against you when contributions are reduced during key earning years.
The type of pension you hold also matters. Those in defined benefit schemes may be somewhat shielded, as their eventual payout is linked to salary and years of service rather than the amount personally contributed. However, those in defined contribution schemes bear the full impact of any reduction in contributions. Every amount not paid in is a direct reduction in the final pension pot, with no mechanism to compensate for the shortfall other than contributing more later.


The crisis is also putting pressure on employers. Smaller businesses in particular are feeling the strain of rising operating costs. Some that previously offered generous pension contributions above the legal minimum are finding it harder to maintain those levels. When both employers and employees pull back at the same time, the overall impact on retirement savings becomes even more significant. Employer contributions are effectively a form of additional income, and losing them compounds the damage already being done by reduced personal contributions.
There is a psychological side to this too. When money is tight, retirement feels far away. It becomes easy to deprioritize long-term saving in favor of immediate needs. The problem is that this mindset can stick around even after finances improve. Getting back into the habit of saving after a break takes effort and intention. Many people who intend to increase contributions once things settle down find that other financial priorities continue to take over.
Self-employed workers face a particularly difficult position. Unlike employees, they do not benefit from automatic enrolment or employer contributions. Their pension saving is entirely self-directed, which means it is also entirely self-disciplined. During a cost of living crisis, self-employed individuals are often the quickest to stop pension contributions altogether, as there is no structural safety net to encourage continued saving.
Where possible, keeping up with at least the minimum contribution level is worth the effort. Doing so protects the saving habit and ensures that any employer matching contributions are not lost. Even small, consistent contributions are more valuable than larger ones made irregularly. Speaking with a regulated financial adviser can help identify what is realistic given your personal situation and how to structure contributions in a way that balances present needs with future security.
The cost of living crisis is very real and very pressing. But its effect on pension contributions is creating a quieter, slower-building problem that many people will not feel until retirement arrives. Addressing it now, even in small ways, is far easier than trying to make up for lost time later.