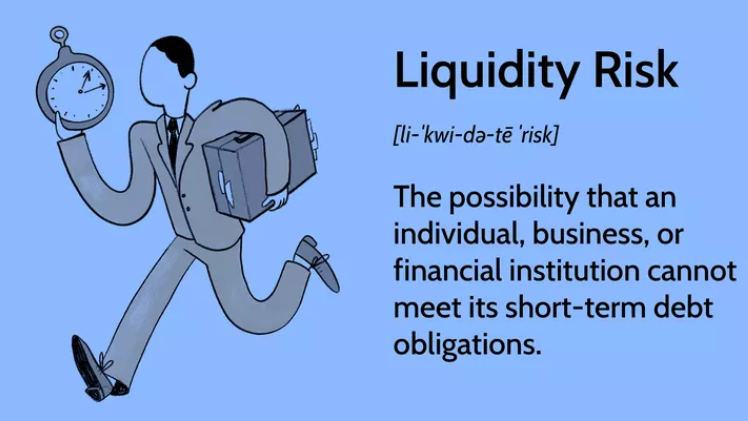
Liquidity is one of the most important, yet sometimes overlooked, considerations in investment analysis. An investment may have attractive returns, strong fundamentals, or a compelling valuation, but these benefits can become difficult to realise if the investor cannot sell the asset quickly without materially affecting its price. This is the essence of liquidity risk: the possibility that an investor may be unable to transact at a reasonable price when the need to buy or sell arises.
Liquidity is particularly relevant when market conditions change rapidly. The recent movement in Kenya’s financial markets provides a useful illustration. During the week ended September 17, 2026, the Nairobi Securities Exchange All Share Index declined by 4.96%, while market capitalisation fell by a similar proportion to approximately KSh3.95 trillion. The decline was followed by a partial recovery on September 18, when market capitalisation rose by KSh56.2 billion to reclaim the KSh4 trillion level.
The episode demonstrates an important distinction between market value and realised value. An investor may hold a security that is technically worth a particular amount based on its quoted market price, but the actual amount received when selling a large position can differ depending on available demand. When there are sufficient buyers and sellers, transactions can generally take place with limited price disruption. When market depth deteriorates, however, even a relatively small order can cause a significant price movement.
One way of assessing liquidity is through trading volume. Higher trading volumes generally indicate greater market participation and make it easier to execute transactions. However, volume should not be considered in isolation. An analyst should also examine bid-ask spreads, the frequency of trading, free float, average daily turnover, and the size of individual transactions relative to normal market activity.

Liquidity also varies significantly across asset classes. Treasury bills and actively traded government bonds can generally provide relatively high liquidity because of the size of the government securities market and the number of institutional participants. Equities differ considerably from one company to another. Large, actively traded companies may have substantial daily turnover, while smaller counters can experience limited trading activity. Private equity, private credit, real estate, and certain structured investments can have significantly longer exit periods because transactions often depend on negotiated sales or specific contractual arrangements.
The recent shift toward government securities in Kenya illustrates another dimension of liquidity. In the September 17 Treasury-bill auction, investors submitted KSh42.7 billion in bids against KSh28.0 billion on offer, equivalent to a subscription rate of 152.6%. The reopened 20-year and 30-year Treasury bonds attracted KSh81.4 billion in bids against KSh60.0 billion offered.
However, liquidity should not be confused with low risk. A liquid asset can still experience substantial price volatility. Similarly, an illiquid asset can generate attractive long-term returns but may expose an investor to significant difficulties when capital is required urgently. Liquidity therefore needs to be assessed alongside market risk, credit risk, duration risk, currency risk, and other relevant factors.
For portfolio managers, liquidity also influences portfolio construction. A portfolio that contains too many illiquid investments may generate difficulties during periods of market stress, particularly when investors simultaneously seek to withdraw funds. This is especially relevant for collective investment schemes, pension funds, insurance companies, and other institutions that must manage asset liquidity against potential liabilities and redemption requirements.
Liquidity can also affect valuation. Investors may demand a liquidity premium for holding assets that are difficult to trade. Consequently, two investments with otherwise similar expected cash flows and risk characteristics may command different valuations if one can be bought or sold more easily. In private markets, the absence of continuous price discovery can make valuation more dependent on financial models, comparable transactions, and periodic appraisal processes.
From an investment-analysis perspective, liquidity should therefore form part of the due-diligence process rather than being considered only when an investor wants to exit. Analysts can examine average turnover, trading frequency, bid-ask spreads, free float, ownership concentration, historical trading patterns, and the potential market impact of a sizeable transaction.
Ultimately, the key lesson is that the quoted value of an investment is not necessarily the same as the value that can be realised immediately. Understanding the difference is particularly important during periods of market stress, when liquidity conditions can change rapidly. For investors and portfolio managers, incorporating liquidity considerations into asset allocation, valuation, position sizing, and risk management can provide a more complete assessment of an investment’s actual risk-return characteristics.