Africa’s young and digitally connected population is reshaping the way consumers shop, transfer money and pay for goods and services. As mobile-first lifestyles become increasingly common, younger consumers are placing greater emphasis on speed, convenience, security and seamless digital experiences. This shift is encouraging banks, fintech companies, telecommunications firms and payment providers to redesign payment systems around fewer steps and faster transactions.
Kenya provides a strong example of this transformation. According to the Communications Authority of Kenya’s 2024/25 Consumer Satisfaction Survey, 71.3% of respondents use mobile phones to access e-commerce platforms, compared with 11.7% who use laptops, 9.6% who use tablets and 7.5% who use desktop computers. The figures highlight the central role of mobile devices in the country’s expanding digital economy.
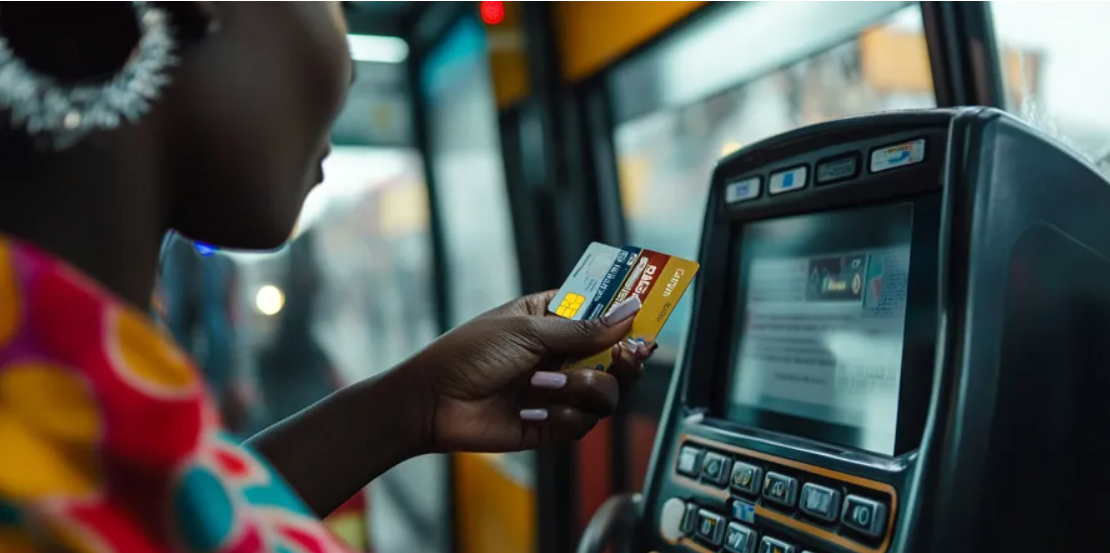
Young consumers increasingly expect payment processes to match the speed of other digital services. Lengthy checkout procedures, repeated password requirements and delayed confirmations can create friction and increase the likelihood that consumers abandon transactions. Frictionless payments aim to remove these barriers through technologies such as QR payments, contactless transactions, one-click checkout and bio metric authentication. These solutions allow consumers to complete transactions with fewer manual steps while maintaining security.
Kenya remains one of the strongest examples of mobile-led financial inclusion. CBK data shows that registered mobile-money accounts reached 95.3 mn by August 2026, up from 89.5 mn in December 2025. During August, mobile-money agents processed 227.4 mn cash-in and cash-out transactions worth Kshs 761.1 bn. While these figures represent registered accounts rather than unique users, they demonstrate the scale and continued integration of mobile money into Kenya’s financial system.
However, the transition toward digital payments remains incomplete. Cash continues to play an important role, particularly among businesses and consumers outside fully digital ecosystems. This creates an opportunity for payment providers to develop solutions that connect mobile money, bank accounts, cards and emerging digital payment platforms rather than treating them as separate systems.
Africa’s fintech sector is also helping move financial services beyond traditional banking infrastructure. Digital platforms can lower barriers to accessing payments while enabling businesses to serve customers through mobile devices.
Kenya’s e-commerce market further reinforces this trend. E-commerce revenues reached approximately USD 86.0 mn in 2025, with double-digit growth expected into 2026. As online commerce expands, payment providers face growing pressure to make the transaction stage as convenient as the shopping experience itself. Greater payment convenience also increases the importance of cyber security and consumer protection. Tokenisation, for example, can replace sensitive card information with device-specific digital tokens, allowing consumers to make payments without repeatedly exposing their underlying card details.
Contactless wearable, QR payments, digital wallets and one-click checkout systems demonstrate how payment technology can increasingly operate in the background. Yet widespread adoption will depend on consumers trusting these systems with their money and personal information.
Africa’s demographic structure provides a long-term catalyst for digital payment adoption. The continent already has the world’s largest youth population, which is expected to more than double to over 830 million by 2050. As this population enters employment, entrepreneurship and consumer markets, demand for connected digital financial services is likely to increase.
The evolution of payments therefore extends beyond replacing cash with mobile transactions. It involves creating an interconnected financial environment where consumers can move from discovering a product to completing a secure payment with minimal interruption. For businesses, payment convenience is increasingly part of the overall customer experience. Every additional step can create friction, while faster and more intuitive payment options can support transaction completion and customer retention.
Young Africans are consequently not simply adopting new payment technologies; their mobile-first behaviour is influencing how the wider financial ecosystem develops. As fintech, mobile money, e-commerce and contactless technologies continue to converge, Africa’s payment landscape is moving toward a model where transactions become faster, more integrated and increasingly embedded in everyday digital experiences.