
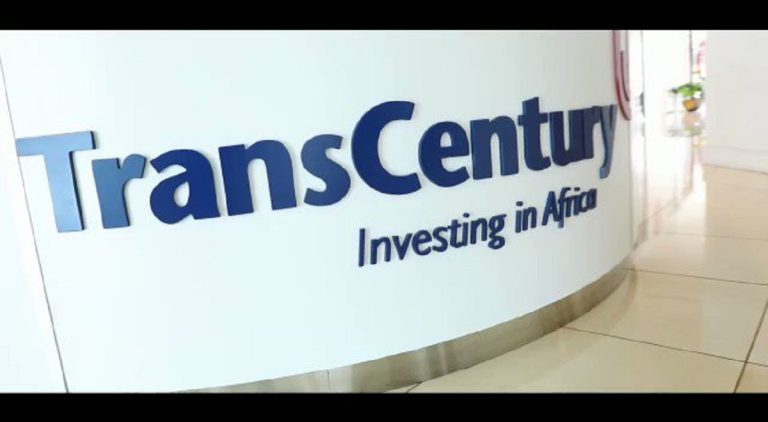
In June 2025, the Capital Markets Authority suspended the trading of TransCentury Limited (TCL) and its subsidiary, East African Cables (EAC), following a receivership initiated by Equity Bank over a KES 4.7 billion debt. This marked a dramatic end to what had once been touted as a turnaround story led by private equity (PE) firm Kuramo Capital and a consortium of prominent Kenyan investors. The losses, estimated at over KES 14.0 billion, have raised concerns within Kenya’s investment community and renewed discussions around the private equity investment model, risk tolerance, and return expectations in frontier markets such as Kenya.
When Kuramo took a controlling stake in TransCentury in 2016 through a KES 2.0 billion rights issue, the goal was clear: to clean up the balance sheet, restructure debt, and refocus operations around core infrastructure assets. But in hindsight, the acquisition may have underestimated the depth of structural and operational weaknesses within the business. TransCentury was burdened with expensive, largely dollar-denominated debt, inherited from its early expansion years. Despite multiple capital injections, these debts, particularly a US dollar-denominated convertible bond, remained a millstone around the company’s neck.
One key lesson from this saga is the importance of realistic turnarounds in PE investing. Frontier markets are uniquely vulnerable to currency depreciation, regulatory shifts, and liquidity constraints. For PE firms, financial engineering alone cannot drive sustainable returns. Operational turnaround requires industry-specific expertise, patient capital, and robust governance, none of which can be outsourced or assumed.
Second, this case lays bare the misalignment of time horizons between local operating environments and PE fund structures. Most PE funds are closed-end vehicles with a 5 to 7- year investment window. But infrastructure, manufacturing, and legacy businesses like TransCentury often require a much longer horizon to yield transformation. Kuramo’s exit was likely stymied by macro conditions, as well as by a mismatch between fund timelines and business realities.
Third, there is a need to re-evaluate how private capital engages with distressed firms. The Kuramo-TransCentury experience suggests that without a coordinated framework, combining capital restructuring, legal safeguards, and creditor alignment, private equity risks becoming a stopgap rather than a solution. Kenya’s weak insolvency resolution mechanisms and patchy judicial timelines only exacerbate this problem.
Yet, this failure shouldn’t be seen as an indictment of private equity as an asset class in Africa. Rather, it’s a call for greater transparency, local alignment, and downside risk planning. PE firms need to move beyond deal execution to become true partners in operational transformation. At the same time, local institutional investors must apply greater scrutiny in co-investment decisions, demanding stronger governance and exit clarity.
The Kuramo debacle will likely have chilling effects in the short term, but it offers hard-earned lessons for a maturing private capital ecosystem. If taken seriously, it could mark the beginning of a more disciplined, locally grounded, and impact-conscious era for private equity in Africa.