
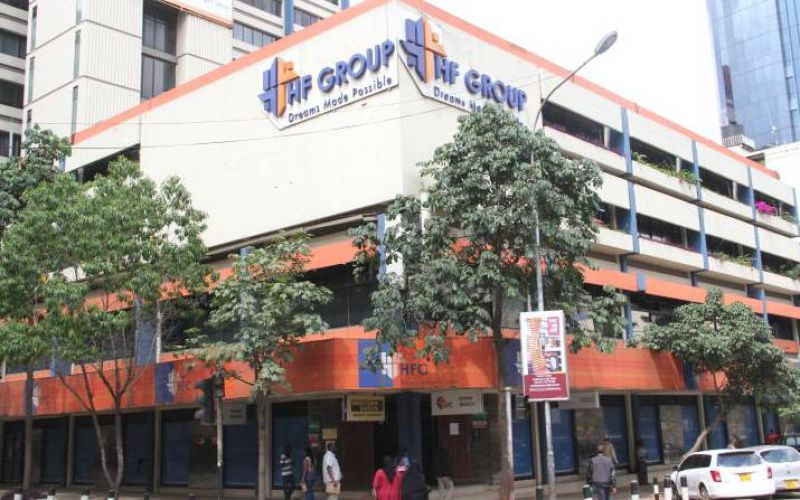
Housing Finance has emerged with the highest lending margins in the Kenyan banking sector, according to the latest data released by the Central Bank of Kenya (CBK). Lending margins, which reflect the difference between interest earned on loans and the cost of funding, are a key indicator of bank profitability, risk pricing, and operating efficiency within the financial system.
The data points to a widening gap between lending rates and deposit costs at Housing Finance, highlighting how the institution has positioned itself amid changing monetary conditions and evolving credit risk. Higher lending margins can indicate stronger earnings potential, but they may also reflect elevated risk profiles, funding constraints, or a cautious approach to lending in uncertain economic environments.
Housing Finance’s business model, which has traditionally focused on mortgage and property-related lending, exposes it to longer loan tenures and sector-specific risks. In periods of economic adjustment, banks with concentrated portfolios may price credit more conservatively to manage default risk and protect balance sheets. This can translate into higher lending margins, particularly when deposit costs remain relatively contained.
The broader banking sector has been navigating a shifting interest rate environment following changes in monetary policy, inflation trends, and liquidity conditions. As the Central Bank adjusts policy tools to support economic stability, banks respond by recalibrating lending and deposit rates to maintain profitability while managing credit demand. Variations in margins across institutions reflect differences in funding structures, asset quality, and strategic focus.
Higher lending margins also have implications for borrowers, particularly households and businesses seeking credit. Elevated margins can increase the cost of borrowing, potentially dampening demand for loans in sectors such as housing, construction, and small business financing. At the same time, stronger margins can enhance bank resilience, enabling institutions to absorb shocks and maintain capital adequacy.
For investors and savers, CBK banking data provides insight into how financial institutions are adapting to prevailing conditions. Profitability indicators such as lending margins influence bank valuations, dividend capacity, and long-term sustainability. However, they also underscore the importance of understanding the broader financial landscape when making investment decisions.
Periods of higher borrowing costs often prompt individuals to reassess their financial strategies, placing greater emphasis on savings, liquidity, and capital preservation. As credit becomes more expensive, maintaining accessible savings can help households manage expenses, reduce reliance on borrowing, and navigate economic uncertainty.
Money market funds continue to play an important role in this context by offering steady returns, low volatility, and easy access to funds. They provide an alternative for individuals seeking to grow their savings while remaining flexible, particularly when lending conditions tighten and borrowing becomes less attractive.
As the banking sector continues to adjust to policy changes and economic trends, lending margins will remain a closely watched indicator. Housing Finance’s position at the top of the margin rankings highlights the diverse strategies within the sector and the ongoing balance between profitability, risk management, and market access.
As financial conditions evolve and borrowing costs fluctuate, maintaining a flexible and stable savings strategy is essential. Consider growing your savings with the Cytonn Money Market Fund (CMMF) a transparent, liquid investment option designed to help you earn steady returns while keeping your funds accessible.
📞 Call +254 (0) 709 101 200 or 📧 email sales@cytonn.com to learn more.