
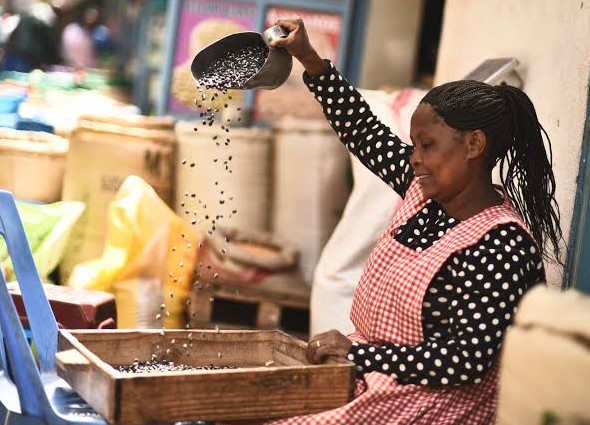
Kenya’s expanding informal economy is creating a significant opportunity for the insurance industry as insurers seek to serve customers whose income patterns differ from those traditionally targeted by conventional insurance products. The growth of irregular, seasonal and transaction-based incomes is increasing the need for products with more flexible payment structures, while also creating opportunities for insurers that can develop efficient distribution models for underserved segments.
The scale of the potential market is significant. Informal employment increased by 4.0% to 18.1 mn jobs in 2025 from 17.4 mn in 2024, accounting for nearly 84% of total employment outside small scale agriculture. This provides insurers with a large potential customer base, but the characteristics of this market create different requirements from those associated with salaried employment. Workers and businesses with variable incomes may find annual premiums or fixed monthly payments less compatible with their cash-flow patterns.
Product development within the insurance sector indicates that insurers are already responding to changing market requirements. During the first quarter of 2026, 28 new or repackaged insurance products were filed with the Insurance Regulatory Authority (IRA). The increase in product activity points to continued efforts by insurers to develop offerings for different customer segments and adapt insurance products to changing market conditions.
However, expanding insurance coverage requires more than developing lower cost products. The IRA has identified low insurance uptake among underserved populations as an ongoing challenge and has sought to address the issue through initiatives such as Bima Mashinani, which focuses on improving insurance access and financial literacy. During an outreach programme in Laikipia in March 2026, the regulator engaged traders, farmers and other community groups, with discussions highlighting concerns around access, trust, claims processes and limited understanding of insurance products.
These challenges are important from an investment perspective because they indicate that insurance penetration is influenced by both product affordability and distribution efficiency. For customers operating outside the formal economy, proximity to insurance providers, ease of payment, clarity of product terms and confidence in the claims process can determine whether insurance becomes a recurring financial product. This creates an opportunity for insurers that can combine product innovation with efficient distribution and customer education.
The emergence of specialized microinsurance operations also demonstrates the industry’s response. Companies including Britam Microinsurance and CIC Microinsurance have developed dedicated operations targeting underserved segments, reflecting growing recognition that low income and informal sector customers may require specialized products and distribution channels rather than simply lower premiums.
The regulatory framework provides additional support for this segment. The IRA recognizes microinsurance as a distinct class of insurance business, with a minimum paid up capital requirement of Kshs 50 mn, compared with Kshs 400 mn for long-term insurance and Kshs 600 mn for general insurance. The lower capital requirement can reduce barriers to entry and support the development of specialized insurance models focused on underserved customer segments.
For investors, however, the size of the addressable market does not necessarily translate into equivalent profitability. Microinsurance products typically involve relatively small premiums, meaning insurers must achieve substantial customer volumes while maintaining tight control over customer acquisition, administration and claims costs. Digital distribution can potentially improve these economics by reducing transaction costs and allowing insurers to reach customers at greater scale, but profitability will ultimately depend on underwriting discipline, operating efficiency and customer retention.
The informal economy is therefore becoming an important testing ground for the next phase of Kenya’s insurance industry. With 18.1 mn informal jobs representing a substantial share of employment, the opportunity extends beyond simply increasing insurance penetration. The more significant investment question is whether insurers can develop scalable business models that align insurance products, pricing and distribution with the irregular financial patterns of informal workers and businesses. Companies that successfully combine affordability, efficient distribution, appropriate underwriting and customer trust could be better positioned to capture the long-term growth potential of Kenya’s underserved insurance market.