Kenya’s banking sector is undergoing one of its most significant transformations in recent years: the transition to risk-based credit pricing. After years of hesitation, resistance, and regulatory back and forth, commercial banks are now fully adopting a model that links loan interest rates to a borrower’s risk profile. The Central Bank of Kenya (CBK) set the stage in 2025 by introducing the Kenya Shilling Overnight Interbank Average (KESONIA) as the new benchmark reference rate. CBK then directed all variable-rate loans to be priced using KESONIA + a risk-based premium, which must reflect the borrower’s creditworthiness. This replaced the old tendency for banks to price loans uniformly, without adequately differentiating their risk profile.
For years, banks pushed back on the model, arguing that it was difficult to price risk accurately in a market with large informal sectors, patchy credit histories, and inconsistent financial reporting. They feared that strict risk-based pricing could expose them to regulatory scrutiny or dampen credit growth. But with the regulator now insisting on transparency and standardized disclosure, banks have shifted their stance, partly because a uniform pricing system exposed them to higher default risks and weak lending margins.
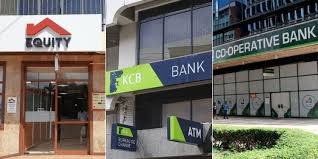
Beginning late 2025, major lenders including Equity Bank, KCB Bank Kenya, Co-operative Bank of Kenya, Stanbic Bank Kenya, and several mid-tier players, started rolling out the new pricing framework for fresh loans. Existing variable-rate borrowers are expected to transition by early 2026. Under the new model, customers with strong repayment histories, stable incomes, or solid collateral will enjoy lower premiums, while those with irregular income patterns or poor credit scores will pay more.
This shift benefits borrowers by creating greater pricing fairness, disciplined borrowers are no longer subsidizing high-risk clients. Secondly, the model enhances transparency, with CBK requiring banks to publish their reference rates, risk premiums, fees, and total cost of credit. For SMEs and salaried professionals with clean credit records, this could mean cheaper access to financing. However, the system also poses challenges. Borrowers in the informal sector, who often lack credit histories or formal income documentation, may find themselves classified as high risk, pushing interest rates upward. Some analysts warn that if not carefully implemented, the model could widen financial exclusion or shift more borrowers toward digital lenders, who already charge far higher rates.
Even so, risk-based pricing is a necessary evolution. Kenya’s economy needs a credit market that rewards good behavior, prices risk accurately, and avoids blanket interest-rate distortions. For banks, the shift brings better risk management. For borrowers, it promises fairer pricing, provided the industry maintains transparency and avoids penalizing vulnerable groups.