
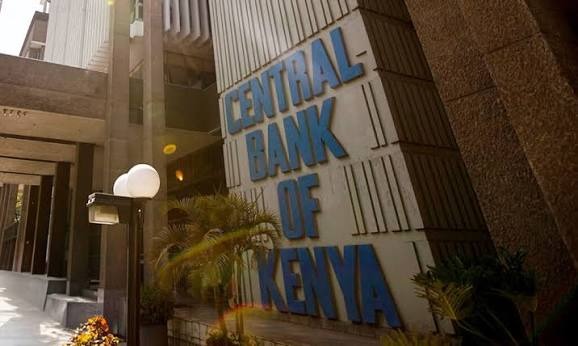
Kenya’s Central Bank Holds Interest Rates at 8.75% Amid Rising Inflation Concerns
The Central Bank Rate (CBR) is a key tool the Central Bank of Kenya (CBK) uses to control inflation and influence borrowing costs. On 7 October 2026, the Monetary Policy Committee (MPC) kept the rate at 8.75%.
The decision comes amid several economic pressures. Global oil prices remain high due to supply disruptions linked to the Middle East conflict. Major economies are also maintaining tight monetary policies. Meanwhile, Kenya’s inflation rate is approaching the upper limit of the CBK’s target range. However, lower bank lending rates are helping private-sector credit recover.
The Decision in Brief
The MPC maintained the Central Bank Rate at 8.75% to keep inflation under control and support exchange rate stability.
Four main factors informed the decision. First, global energy prices remain elevated, threatening to raise fuel and transport costs. Second, inflation is expected to remain within the target range in the near term. Monetary policy, government subsidies, temporary VAT relief on fuel and a stable shilling should provide support.
Third, major central banks remain cautious about interest rates. Finally, lower commercial bank lending rates have helped private-sector credit growth recover.
The CBK will continue monitoring global oil prices and their effects on domestic inflation. It remains ready to adjust monetary policy if conditions change. This signals a cautious, data-driven approach rather than a commitment to further rate cuts.
Inflation Is Rising Towards the Upper Limit
Kenya’s headline inflation rose to 6.8% in September 2026, from 6.6% in August. The CBK targets inflation at 5.0%, with an allowable range of 2.5% to 7.5%. Inflation remains within this range but is moving closer to its upper limit.
Core inflation, which excludes certain volatile items, rose to 4.0% in September. This compares with 3.4% in August and 2.0% in December 2025. Higher prices for processed foods, including milk, wheat products and edible oils, contributed to the increase. Transport-related costs also played a role.
Food and Energy Prices Remain Important
Non-core inflation includes volatile items such as food and energy. It eased to 14.0% in September, from 14.7% in August and a peak of 16.0% in May. This suggests that price pressures in some categories have moderated, although they remain elevated.
The distinction between core and non-core inflation matters. Some recent relief in volatile prices has depended on government interventions. These include fuel subsidies and temporary VAT relief. Meanwhile, rising core inflation suggests that underlying price pressures deserve attention.
Inflation Could Approach 7.5%
CBK projections indicate that inflation could rise to 6.9% in October, 7.1% in November and 7.2% in December. It is then expected to decline to 5.0% by May 2027 and 4.8% by September 2027.
A December peak of 7.2% would leave just 0.3 percentage points below the upper limit of the target range. This narrow margin could limit the CBK’s room to ease monetary policy further if inflation exceeds expectations.
The Central Bank Rate currently stands 1.95 percentage points above headline inflation. If inflation reaches 7.2%, the difference would narrow to 1.55 percentage points. This is a simple comparison, rather than a measure of the expected real interest rate.
Inflation expectations remain relatively stable. Surveys show that banks expect inflation of about 6.9%, while non-bank businesses expect approximately 6.7%. Respondents also anticipate some relief in food prices if rainfall between October and December is above average.
Global Developments Could Put Pressure on Kenya
International developments remain important to Kenya’s monetary policy. Murban crude oil was trading at around USD 96 per barrel in the latest reading. This was below its April peak of USD 102.7. However, elevated oil prices still threaten to raise domestic fuel, transport and production costs.
The IMF projects global inflation at 4.7% in 2026, up from its earlier forecast of 4.4%. The US Federal Reserve and European Central Bank have each raised interest rates by 25 basis points at their latest meetings. Meanwhile, the Bank of England and Bank of Canada have held their rates. The OECD expects global economic growth to slow to 2.9% in 2026.
Higher Global Rates Raise Borrowing Costs
Higher interest rates in major economies can make international borrowing more expensive for emerging markets, including Kenya. The CBK has noted tighter global financial conditions. Some emerging and developing economies have experienced higher Eurobond yields and weaker equity markets.
For Kenya, higher global borrowing costs could increase the expense of issuing international bonds or refinancing existing debt. They may also affect investor demand for Kenyan assets and the cost of financing public and private investment.
Interest Rates, Bank Lending and Credit Growth
The CBK uses the Central Bank Rate to influence short-term interest rates across the financial system. Under the current framework, the Kenya Shilling Overnight Interbank Average (KESONIA) is guided by a corridor around the CBR.
The corridor has narrowed from 250 basis points on either side of the policy rate to 50 basis points. This helps short-term market rates track the policy rate more closely.
How Risk-Based Credit Pricing Works
The revised Risk-Based Credit Pricing Model has been fully operational since March 2026. It links the cost of eligible variable-rate loans to KESONIA, a bank-specific premium and applicable fees and charges. The model excludes foreign-currency loans and fixed-rate loans.
The framework aims to improve transparency. It should make it easier for borrowers to understand how banks determine lending rates and the total cost of credit.
Lending Rates Are Falling as Credit Recovers
The average commercial bank lending rate declined to 14.4% in September 2026, from a peak of 17.2% in late 2024. The average deposit rate stood at 6.9%. This left a difference of approximately 7.5 percentage points between lending and deposit rates.
Lower lending rates have coincided with a recovery in private-sector credit. Credit growth reached 10.6% in September, compared with a contraction of 2.9% in January 2025. Broad money supply, which measures cash and various forms of money held in the economy, grew by 11.3%.
Credit Growth Varies Across Sectors
Credit growth has not been uniform across the economy. Lending to agriculture grew by 32.5%, while finance and insurance expanded by 28.6%. Trade recorded growth of 19.2%, followed by building and construction at 12.9% and consumer durables at 12.7%.
Manufacturing moved in the opposite direction. Credit to the sector contracted by 1.8%.
This decline is worth monitoring because the CBK expects manufacturing to grow by 3.2% in 2026. It suggests that the wider recovery in lending has yet to translate into stronger borrowing across every part of the economy.
The Shilling and Foreign Exchange Reserves
Kenya’s external position remains important to the CBK’s decision. The current account deficit is projected to widen to 3.2% of GDP in 2026, from 2.1% in 2025. It is expected to reach 3.5% in 2027.
Imports Are Growing Faster Than Exports
In the 12 months to August 2026, goods imports increased by 15.8% to USD 27.2 billion. The main drivers were food, fuel and capital goods. Goods exports rose by 11.8% to USD 14.4 billion, supported by horticulture, tea and machinery.
Services receipts increased by 8.7% to USD 8.9 billion. However, diaspora remittances declined by 1.3% to approximately USD 5.0 billion. This partly reflected lower inflows from the United States and Saudi Arabia.
Despite the wider current account deficit, the CBK expects financial and capital inflows to cover the shortfall. This should produce an overall balance of payments surplus of about USD 2.4 billion in 2026.
Reserves Provide a Buffer Against External Shocks
Foreign exchange reserves stood at USD 14.7 billion on 6 October 2026. This was equivalent to 5.9 months of import cover, compared with 3.4 months in 2023. These reserves help Kenya meet external payment obligations and manage pressure on the shilling.
The shilling was trading at approximately Kshs 129.7 against the US dollar. It had remained broadly stable over the preceding two years.
This stability helps importers plan costs and reduces uncertainty for businesses with foreign-currency obligations. However, the projected widening of the current account deficit and the decline in remittances remain potential sources of external pressure.
Economic Growth, Banking Stability and Government Borrowing
The CBK has revised its 2026 economic growth forecast upward to 5.0%, from 4.9%. This follows growth of 4.6% in 2025. The economy is expected to expand by 5.3% in 2027, supported by industry and services.
Construction is projected to grow by 7.2%, while agriculture is expected to expand by 3.0%. Agricultural performance remains sensitive to weather conditions. The forecast El Niño rains could affect both food production and prices.
Banks Remain Well Capitalised
The CBK describes Kenya’s banking sector as stable. The capital adequacy ratio, which measures banks’ capacity to absorb losses, stood at 20.5% in August. This was above the regulatory minimum of 14.5%.
The liquidity ratio was 59.8%, against the required minimum of 20.0%. Meanwhile, the gross non-performing loan ratio declined to 13.9% in September, from 17.6% a year earlier.
These figures point to stronger asset quality and substantial capital and liquidity buffers. However, the remaining level of non-performing loans still warrants attention.
The Budget Deficit Remains a Concern
Fiscal policy presents a more mixed picture. Kenya’s budget deficit stood at 6.8% of GDP in the 2025/26 financial year. It is projected to narrow to 5.5% in 2026/27 before rising to 5.9% in 2027/28. The deficit is then expected to decline to 5.1% by 2029/30.
The government therefore expects to reduce borrowing relative to the size of the economy over time. However, the adjustment is unlikely to be smooth. Continued government borrowing could influence domestic interest rates and the availability of funds for private-sector investment.
What the Central Bank Rate Decision Means for Investors
The decision to hold the CBR at 8.75% has implications for fixed-income investors, banks and businesses. Its effects will depend on how inflation, credit demand and government borrowing evolve.
Implications for Fixed-Income Investors
A steady Central Bank Rate provides a relatively stable reference point for short-term interest rates. Short-term Treasury bill rates have remained broadly aligned with the policy rate.
This suggests limited immediate change in the shorter end of the yield curve. However, actual bond yields will also depend on inflation expectations, government borrowing needs, market liquidity and investor demand.
Implications for Banks and Borrowers
For banks, improving credit growth and falling non-performing loans point to a more supportive operating environment. Capital and liquidity ratios also remain above regulatory minimums.
However, the Risk-Based Credit Pricing Model could put pressure on lending margins. This may happen if lending rates decline while deposit costs adjust more slowly. Sustained growth in lending volumes will therefore be important.
For businesses, lower borrowing costs can make working capital, investment and expansion more affordable. However, the benefits differ across sectors. The contrasting credit growth figures for agriculture, trade and manufacturing illustrate this uneven recovery.
Implications for the Shilling and Businesses
Currency stability and adequate foreign exchange reserves provide some protection against external shocks. Nevertheless, higher global interest rates, a wider current account deficit and weaker remittance inflows remain risks.
Businesses that rely heavily on imported fuel and other commodities are also exposed to international price movements, even when the shilling remains stable.
Inflation Will Determine the Next Move
The CBK’s decision to maintain the Central Bank Rate at 8.75% reflects a balance between rising inflation risks and improving domestic economic conditions. Inflation remains within the target range, but projections suggest it could approach the upper limit by December 2026.
At the same time, private-sector credit growth has recovered, commercial lending rates have declined and the shilling remains stable. The challenge is to sustain these gains without reigniting inflation or increasing pressure on Kenya’s external position.
Global oil prices, domestic food costs, government borrowing and the transmission of lower policy rates to borrowers will remain important factors to watch. The CBK has indicated that it will continue assessing incoming economic data and remains prepared to act if necessary. The next review of the Central Bank Rate is scheduled for the December 2026 MPC meeting.