
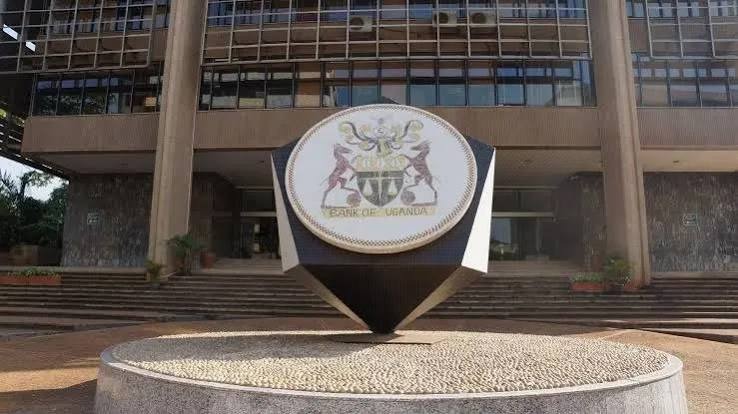
The Bank of Uganda (BoU) Monetary Policy Committee (MPC) raised the Central Bank Rate (CBR) by 225.0 basis points to 12.0% in October 2026, from 9.75%, marking a shift towards tighter monetary policy amid rising inflation risks and pressure on the Ugandan shilling. The decision followed an increase in the Cash Reserve Requirement (CRR) to 13.5% from 11.0%, effective 24 September 2026, as the central bank moved to contain inflationary pressures and strengthen monetary policy transmission.
The decision reflects a deterioration in the external environment, with escalating geopolitical tensions in the Middle East contributing to higher global oil prices, freight costs and uncertainty in international financial markets. Uganda’s headline inflation rose to 4.6% in September 2026, from 4.1% in August, while core inflation increased to 3.7% from 3.5%. Although core inflation remains below the medium-term target of 5.0%, the weakening shilling and higher fuel prices risk increasing the cost of imported goods and spreading price pressures across the economy. Consequently, the BoU revised its inflation outlook upwards, projecting headline inflation of 7.0%-7.5% and core inflation of 5.5%-6.0% over the next 12 months.
However, the tightening comes amid a moderation in economic growth. The BoU revised its FY2026/27 growth forecast downwards to 6.0%-6.5%, from an earlier projection of 7.0%-7.5%, reflecting tighter financial conditions, exchange-rate depreciation and elevated energy prices. Higher interest rates could help contain inflation and support currency stability, but they may also increase borrowing costs for businesses and households, potentially weighing on private investment and consumption.
For investors, the rate hike could support yields on government securities and improve returns on shilling-denominated fixed-income investments, although the actual outcome will depend on market expectations and subsequent monetary policy decisions. Banks could benefit from higher lending rates, but increased borrowing costs may also constrain credit demand and affect asset quality. The shilling’s performance, inflation trends and the duration of external shocks will therefore remain key indicators to monitor.

Going forward, the MPC faces the challenge of containing imported inflation without unnecessarily constraining economic activity. The effectiveness of the latest tightening will depend on whether it stabilises the exchange rate, anchors inflation expectations and limits the pass-through of higher fuel prices into domestic prices.
Start your investment journey today with the Cytonn Money Market Fund. Call + 254 (0)709101200 or email sales@cytonn.com