Kenya’s macroeconomic landscape in 2025 reflects a complex blend of resilience and vulnerability, with strong monetary and external fundamentals overshadowed by persistent fiscal pressures and structural impediments to competition. While growth momentum has improved in early 2025, the country’s long-term prospects remain tied to its ability to address deep-rooted regulatory and governance challenges.
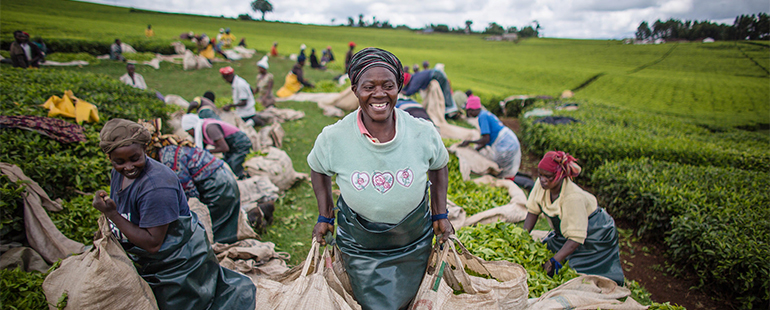
Economic activity slowed to 4.7% in 2024, weighed down by tight monetary conditions, fiscal consolidation efforts, and heightened policy uncertainty following mid-year protests. However, the first two quarters of 2025 indicate a steady rebound, with GDP expanding by 4.9% and 5.0% respectively. Agriculture and services, the backbone of Kenya’s production structure, continue to underpin growth, supported by favourable weather and resilient domestic demand. The construction sector, which had contracted earlier, is now recovering on the back of lower interest rates and government clearance of road arrears.
Monetary policy has been a key stabilizing anchor. Headline inflation has stayed within the Central Bank’s 5.0% ±2.5% target band, supported by easing global supply chain pressures and prudent monetary management. The Kenya shilling has remained broadly stable against the US dollar, bolstered by robust remittances, tourism receipts, and record-high foreign exchange reserves exceeding USD 10.0 Bn. Private sector credit, previously constrained by high lending rates, is showing signs of revival as rates decline and liquidity conditions improve.
Yet Kenya’s fiscal position remains its most significant macroeconomic challenge. Fiscal consolidation targets continue to slip, with the FY2024/25 deficit widening to 5.9% of GDP against a 4.3% target. Revenue underperformance, particularly in income and excise taxes, combined with mounting expenditure pressures has forced additional reliance on domestic borrowing. This has, in turn, exacerbated crowding-out effects, with commercial banks increasingly favoring government securities over private sector lending. Rising interest payments, now at 5.8% of GDP, signal tightening fiscal space and growing vulnerability.
Public debt has edged up to 68.8% of GDP, maintaining Kenya in high debt distress territory. Although liability management operations, such as the partial restructuring of the Standard Gauge Railway loan and issuance of a USD 1.5 bn Eurobond, have eased near-term refinancing risks, the debt mix continues to shift toward shorter maturities, heightening rollover risks.
Beyond macro-stability, the World Bank report highlights structural constraints rooted in Kenya’s competition environment. The country records one of the most restrictive product-market regulation (PMR) scores globally, reflecting barriers linked to state participation in commercial sectors, opaque policymaking processes, and high trade protection. With over 200 state-owned enterprises, including many in competitive sectors, public ownership distorts market incentives and deters private investment. Tariff and non-tariff barriers remain among the highest in peer economies, inflating input costs and weakening the competitiveness of local firms.
Sectoral bottlenecks further reinforce these constraints. Fertilizer distribution reforms have increased farmer travel distances and created shortages, while non-competitive energy procurement practices continue to raise electricity costs. In telecommunications, market dominance remains insufficiently addressed, affecting pricing and digital inclusion.
Addressing these barriers could raise GDP growth by over one percentage point annually and significantly boost job creation. Strengthening SOE governance, broadening regulatory impact assessments, and reducing market entry barriers will be essential to unlocking productivity, investment, and inclusive growth.